Product Overview

A quick look at the GLYNT.AI solution

Audit-Ready Sustainability Data

Prepared for ISSA 5000 and other audit standards

Sustainability Data Layer

Works with the software and AI you already use

Approval Workflows for Sustainability Data

Four-Eyes review for audit compliance

Finance-Grade Sustainability Data

The same rigor as financial data

Integrate with Financial Data

Reconcile against your financial ledger

AI-Ready Sustainability Data

See what’s missing or flagged before deadlines

Powered by Green AI

Built for low energy use and emissions

Best Practices for Sustainability Data Management

Manage data instead of wrangling it

Enterprise Security

Privacy, security, and controls

Sustainability Data Accuracy

We test your data so you don’t have to

Comprehensive File Capture

Extract data from scans, portals, and messy formats

Customized Reporting

See what’s missing or flagged before deadlines

Audits & Assurance

Traceable data, approval workflows with SOC compliance

Business Value Add

Customize output files for CSRD, IFSR, CBAM, UKSRS

Energy Data Management

Granular data for transparency and cost reductions

Waste Data Management

Pull files from everywhere, send data to anywhere

Scope 3 & PCFs

Stop chasing suppliers, move to finance-grade quality

Blog

What’s new with GLYNT

Customer Stories

Industry applications for GLYNT solutions

Guides

GLYNT’s expertise and thought leadership

Why the Politicization of ESG Doesn’t Matter

by | May 23, 2022

In the past two weeks former Vice President Pence has called ESG investing a “radical agenda” and Elon Musk has called it a “scam.” Now worth $35T, ESG investing has captured more than a quarter of all financial assets under management (source). So will ESG investing go away as it becomes politicized? The answer is No, and the reasons lie in the data.

First, consider two future scenarios. Either could happen. In the first scenario, additional policies and investments decarbonize the global economy and the average temperature stabilizes. In the second scenario, our current scattered policies and investment levels continue, and the average temperature keeps rising.

Note that there is not a scenario where current policies don’t lead to temperature rise. The data is clear: this is not a valid option – it is wishful thinking.

Two Future Scenarios
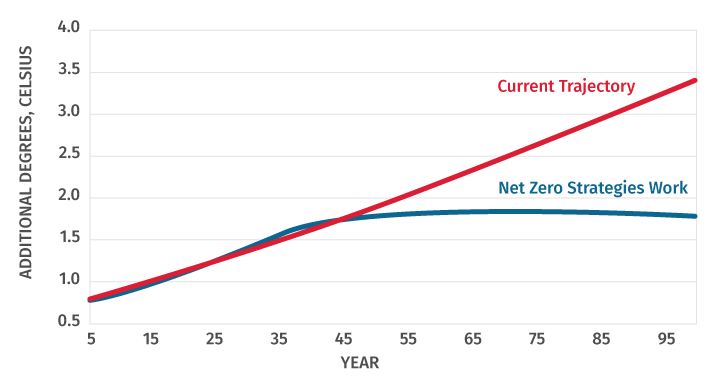
Graph with years on the x axis (5 - 95) and degrees celsius on the y axis (0.5 - 4.0). Two lines are plotted - the first titled "current trajectory" and shown to be rising evenly towards 3.5º over 95 years, and the second titled “net zero strategies work" and shows a line rising and then leveling off after year 35 around 1.75º.

Second, take a look at the cost of each scenario. The big takeaway is that the future looks different than the past. Both future scenarios are costly – there is no escape from some kind of expense.

Comparison of Average Annual GDP Growth
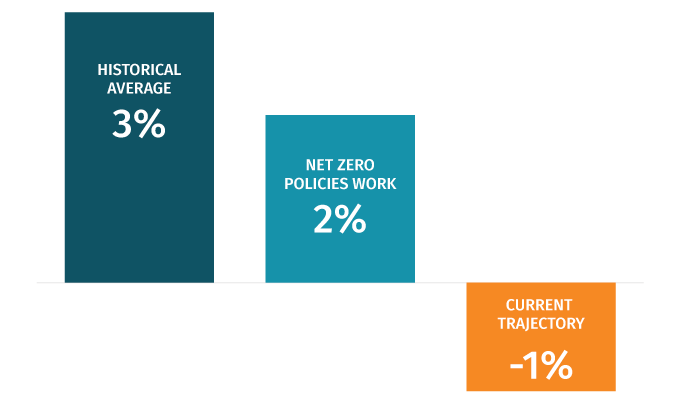
3 blocks on a bar graph. The first block reads “historical average - 3%.” The second reads “net zero policies work: 2%.” The last block is positioned below the graph line and reads “current trajectory: -1%.”

None of us control policy, so acting as individual investors we can pick our scenario and plan accordingly. If we wish to believe Pence, then we would invest as if climate change did not matter to valuations.

Here’s Moody’s take on which sectors could get hit the hardest by the physical risk of climate change, such as more flooding, more heat and so on. If the investment strategy is “Pence is right,” then the investor would ignore this type of analysis. But if the rest of the financial markets are using this data to price risk into stocks, the Pence investor will lose money by ignoring data that is correlated with value.
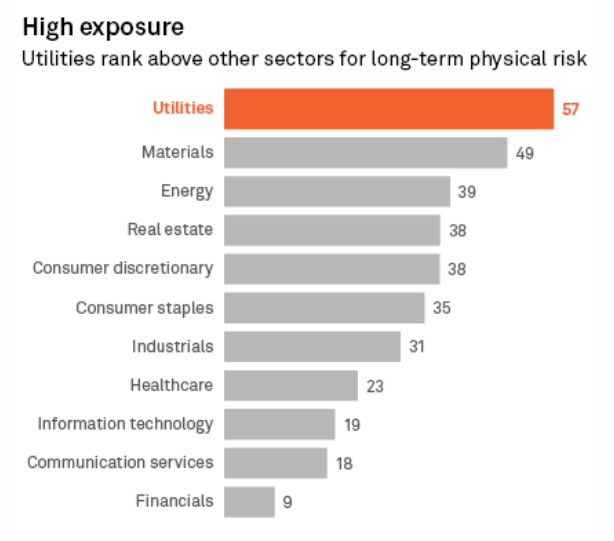
A graph from S&P Global, showing High Exposure in investement sectors. The subheadline on the graph says utilities rank above other sectors for long-term physical risk. Utilities are the first bar in a horizontal, descending bar chart, highlighted at 57. Below that the bars are labeled as materials at 49, energy at 39, real estate and consumer discretionary tied at 38, consumer staples at 35, industrials at 31, healthcare at 23, information technology at 19, communication services at 18, and finally financials at 9.

The bottom line is that climate change makes our economic future different from the past, regardless of political beliefs. Investors who ignore this substantive difference will be the losers. The climate disclosure regulations proposed by the SEC codify a lens as to how corporate valuations are affected by climate change. That lens makes money for investors, and so climate disclosures and analytics are here to stay, regardless of what some politicians and public figures say.

Get Started with GLYNT